 By
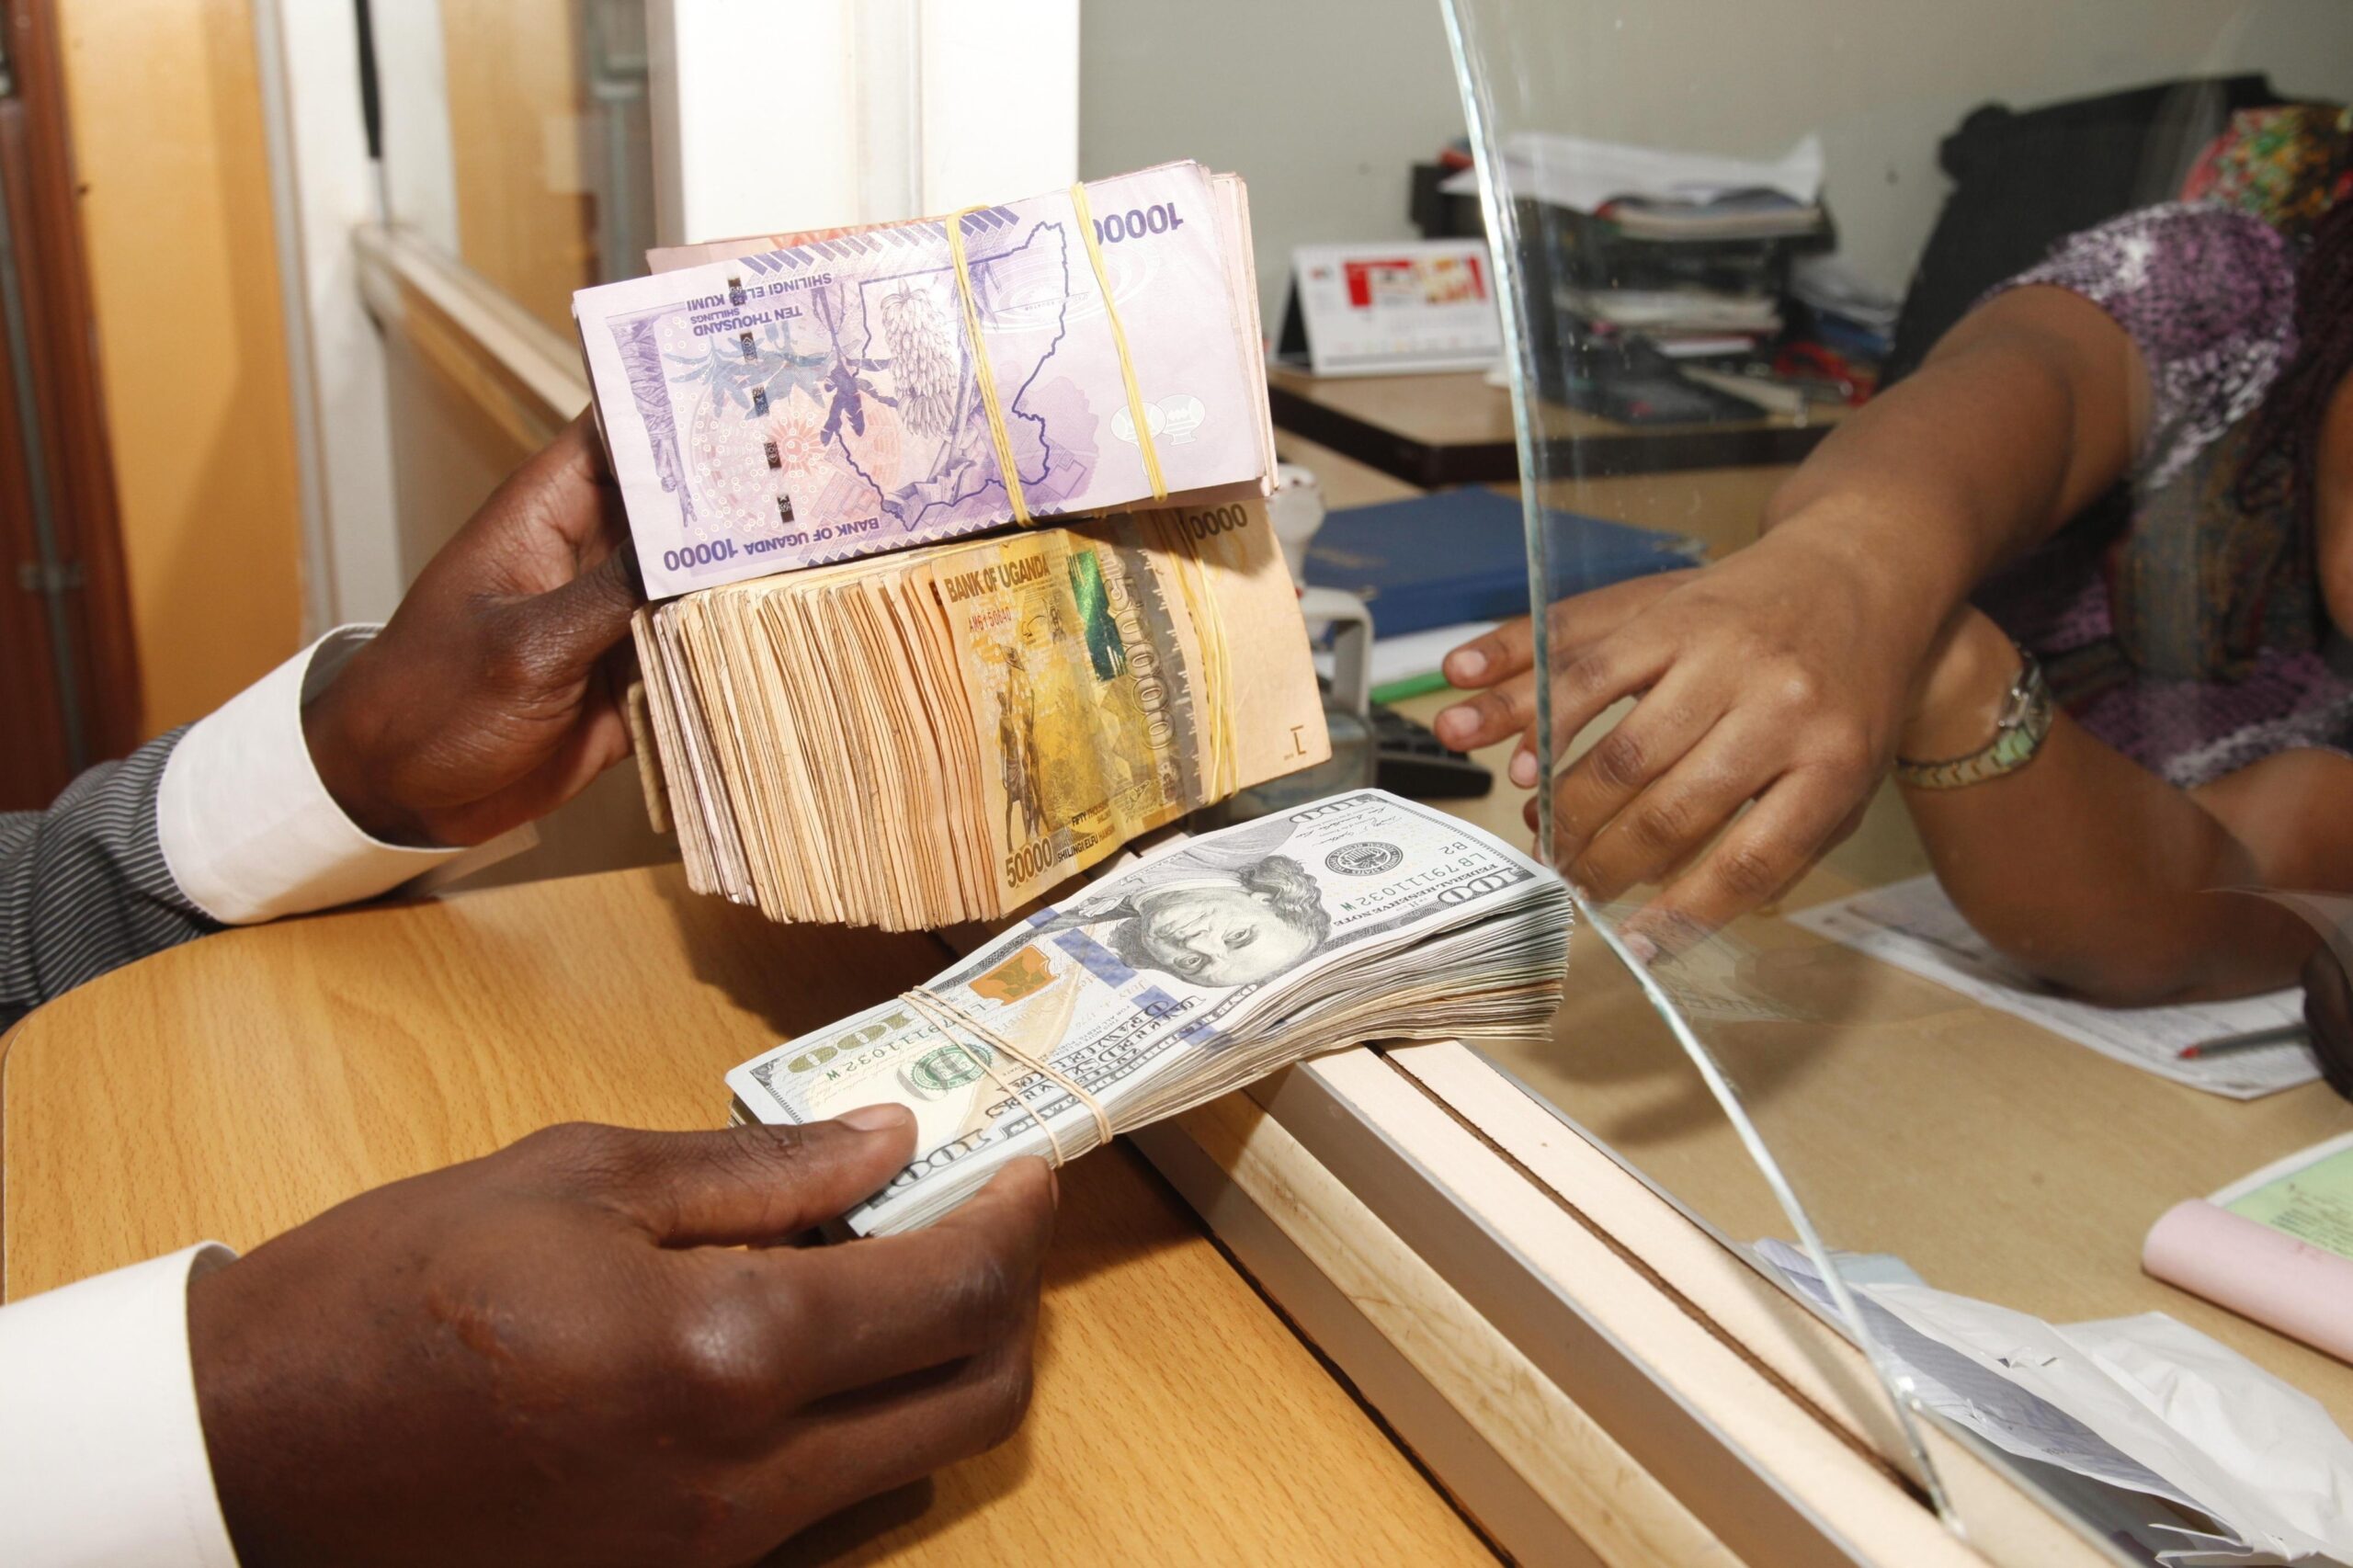
For many Ugandans abroad, investing back home often brings to mind buying a plot of land, constructing rental houses or starting a business with relatives. Yet Uganda’s financial markets offer other options that can be explored without having to manage a physical property from thousands of miles away.
Treasury bills, government bonds and shares allow investors to participate in different parts of the economy. The three work differently, however, and choosing between them begins with understanding what each one offers.
1. Treasury bills: Investing for the shorter term
When the Government of Uganda needs to borrow money, it can issue Treasury bills through the Bank of Uganda. These are short-term investments that typically mature after 91, 182 or 364 days.
In simple terms, an investor lends money to the government for a specified period and receives the agreed return according to the bill’s terms. Treasury bills are commonly bought at a discount to their face value, with the difference representing the investor’s return.
They may appeal to someone saving towards a planned expense or looking for an investment with a relatively short time horizon. However, investors should check the latest auction rates, applicable taxes and fees, and remember that returns are not necessarily the same from one auction to another.
2. Government bonds: Lending for longer
Government bonds also involve lending money to the government, but they generally run for longer periods than Treasury bills.
Depending on the bond’s terms, investors may receive interest payments at regular intervals and have their principal repaid at maturity. They may suit someone planning ahead for a future expense or seeking periodic income.
The important consideration is time. If an investor needs their money before a bond matures, selling it on the secondary market may result in a price higher or lower than the amount originally invested. Longer-term investments also carry inflation and other risks.
The Bank of Uganda publishes information on government securities, including auction results and market rates, through its financial markets section.
Could a government bond be designed specifically for Ugandans abroad? Beyond existing government securities, a dedicated diaspora bond could offer Ugandans living overseas another way to invest in their home country’s development. Ethiopia provides an example of both the potential and the challenges of this approach.
Could Uganda introduce a diaspora bond?
Ethiopia issued bonds aimed at raising money from its diaspora for the Grand Ethiopian Renaissance Dam (GERD), Africa’s largest hydroelectric project. The bond formed part of a wider national fundraising effort, rather than the project’s sole source of financing. However, the diaspora bond raised less money than originally hoped, demonstrating that national pride alone does not guarantee investment. Clear terms, credible repayment arrangements and confidence in how funds are managed are essential.
The Africa Report examines Ethiopia’s experience and the lessons for other African countries.
Uganda has also explored diaspora bonds as a potential source of development financing through its Public Investment Financing Strategy. A well-designed bond tied to a clearly identified project could provide Ugandans abroad with another way to support development at home while earning interest. However, transparent reporting, clear repayment terms and accessible purchasing arrangements would be essential to building investor confidence.
A diaspora bond would be an investment, not a donation. For now, it is a potential opportunity to explore, not confirmation that a dedicated Ugandan diaspora bond is available for purchase.
3. Shares: Owning a piece of a company
Unlike government securities, shares represent ownership in a company. Through the Uganda Securities Exchange (USE), investors can buy shares in listed companies and potentially benefit from dividends or an increase in the share price.
But neither outcome is guaranteed. A company may not pay dividends, and its share price can fall, leaving an investor with less than they paid.
The USE says investors can open a Securities Central Depository (SCD) account through a licensed stockbroker. This account records their shareholdings. Its investor FAQs explain the process of buying and selling shares.
Can Ugandans abroad invest without travelling home?
Potentially, yes. The Uganda Securities Exchange recognises local, East African and foreign individual investors, but the documents and procedures required depend on the investor’s circumstances and the type of investment.
For shares, contact a licensed Ugandan stockbroker to establish whether an account can be opened remotely, which identification and source-of-funds documents are required, and how deposits, dividends and sale proceeds will be handled.
For Treasury bills and government bonds, contact a participating bank or the Bank of Uganda to confirm the account-opening procedure, eligibility, minimum investment and payment arrangements for someone living overseas. Do not assume that the process is identical for every investor.
Before transferring money, verify the intermediary’s credentials with the relevant regulator and obtain a written breakdown of all fees, taxes and currency-conversion costs.
What should diaspora investors consider first?
The right investment depends on what the money is meant to achieve. Someone who may need their savings soon has different priorities from someone investing for ten years. Investors should also consider the exchange rate: converting pounds, dollars or euros into shillings, and later converting the proceeds back, can affect the overall return.
It is also important not to put all one’s savings into a single investment. The Capital Markets Authority advises investors to research what they are buying, seek advice from a licensed investment adviser and diversify rather than concentrate their money in one place.
For Ugandans abroad, investing at home need not begin with a large commitment. It can begin with understanding the available options, checking the actual costs and choosing an amount they can afford to leave invested.
Useful Resources for Diaspora Investors
Before investing, consult these institutions for official information, investor guidance and applicable requirements.
- Bank of Uganda: Treasury bills and government bonds
- Uganda Securities Exchange: Investor FAQs
- Capital Markets Authority Uganda: Investment tips
- Ministry of Finance: Public Investment Financing Strategy, which discusses potential financing options, including diaspora bonds.
Note: Investment terms, rates, fees, taxes and eligibility requirements may change. Confirm the latest details with the relevant institution or a licensed financial intermediary before investing. A potential diaspora bond should not be treated as an available investment unless an official issuance is announced.